
Two Chinas
Published . By Devin Shutte, Head of Investments.
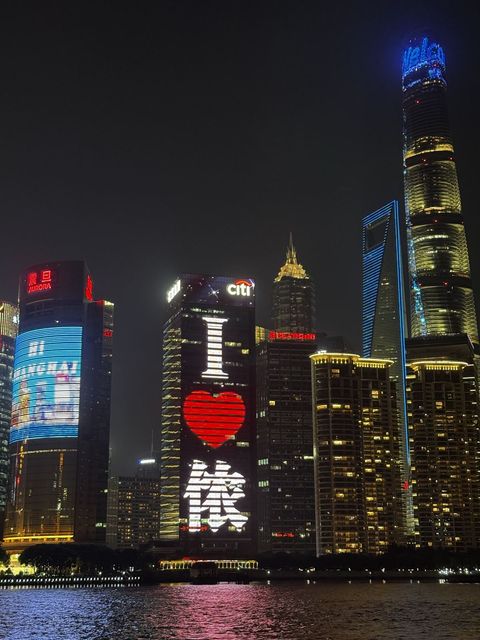
Nine days, three cities and eight companies. China’s factories and technology are running well ahead of its households.
We allocate client capital to China, so in October we went to see it for ourselves: factory floors, bullet trains and hotpot tables in Shanghai, Beijing and Chengdu.
The tour was organised by Prescient, the manager we use for Chinese equities, and TRG paid its own way. We met an AI lab, a car plant, the world’s largest polysilicon producer, a satellite-navigation company, a 600-year-old baijiu distillery and one of China’s largest brokerages, and spent the time between on the street.
25 to 26 Oct, 31 Oct to 1 Nov
Shanghai
A brokerage, machine tools, satellite navigation and Prescient’s China office.
27 to 28 Oct
Beijing
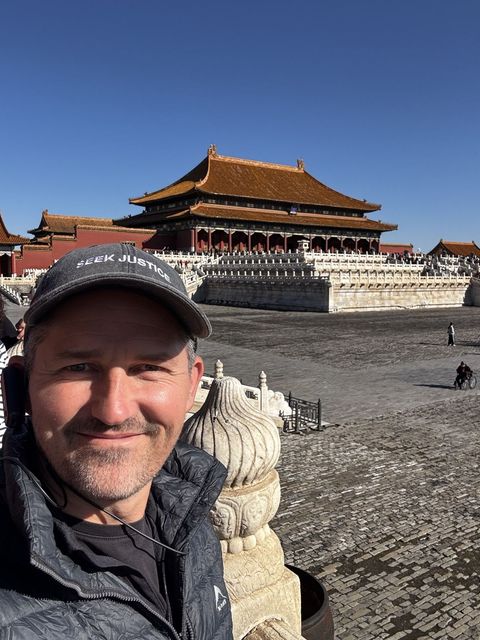
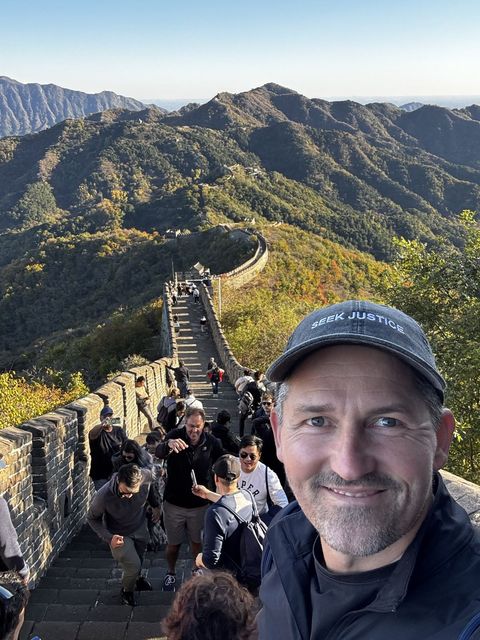
The Forbidden City, the Great Wall and two of China’s AI companies.
29 to 30 Oct
Chengdu
Pandas, teahouses, a Geely car plant, polysilicon and baijiu.
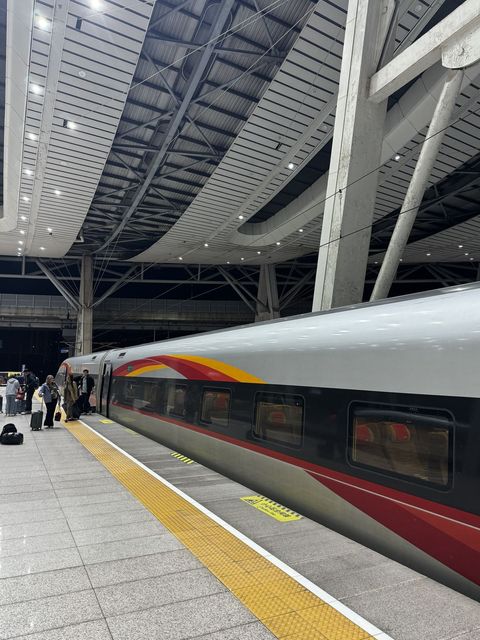
Production and the consumer
China’s economy grew 4.5% in the third quarter. Retail sales grew 1.1% in September.
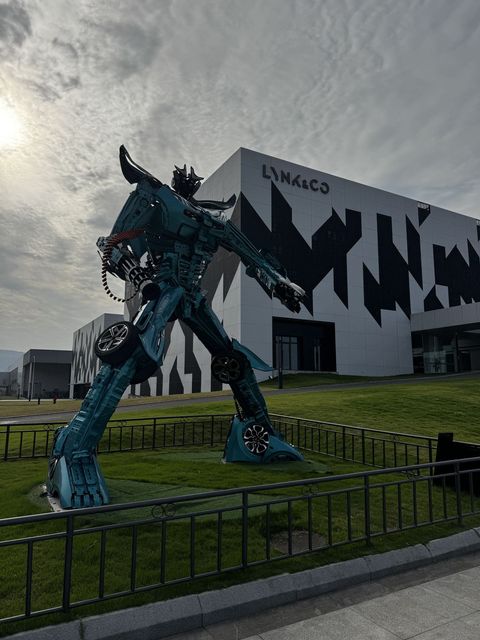
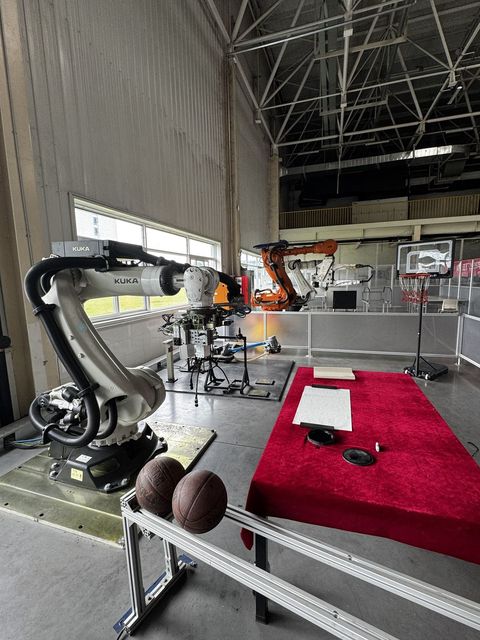
At Geely’s Lynk & Co plant in Chengdu, management told us the line builds a car in under a minute, about 400 000 a year, with robots doing most of the work. Many of those robots are KUKA arms: German by design, and owned by China’s Midea since 2017.
Households are cautious. They lost twice: property prices stopped rising, and trust products that promised 8% to 10% a year, “pretty much risk free”, failed. Families now save and wait, and with prices falling, waiting is rewarded. Next year’s phone or car costs less.
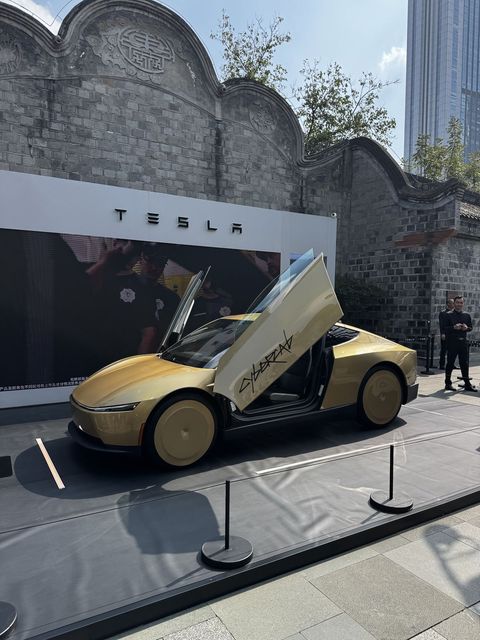
Spending has shifted to essentials, services and travel, while cars, furniture, building materials and jewellery are falling. The streets, trains and tourist sites were full. Luckin Coffee alone runs 36 310 stores, more than twice Starbucks’ US store count.
Technology
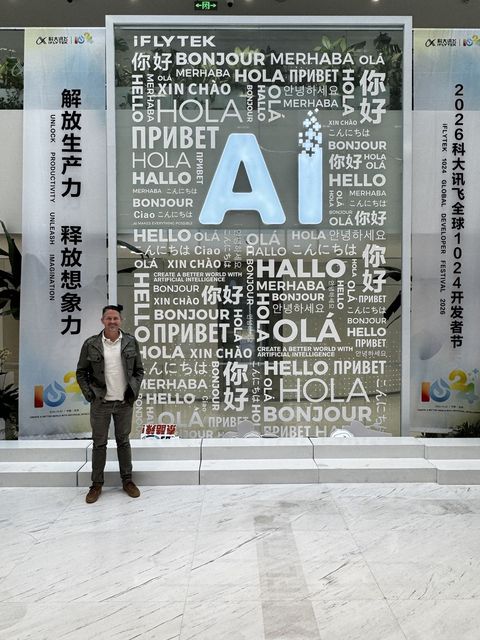
In Beijing we met Zhipu, one of China’s leading AI labs, and iFlytek, the speech and language specialist. Zhipu runs about a tenth of its computing on Nvidia chips and prices its fastest model at a tenth of its flagship. It told us annualised revenue reached US$1.8 billion in September. iFlytek trains its Spark model entirely on Chinese-made chips.
US export controls have slowed China’s AI industry, and it is still shipping competitive models at low prices. That keeps pressure on AI margins everywhere, including in the US.
Growth and returns
China’s economy grew about 4.6% in the first nine months of 2026. Over the same period the MSCI China index fell about 13% in US dollars.
The company visits showed why. A satellite-navigation company with 60% gross margins and exports up 35% reported nine-month profit down 25%. The world’s largest polysilicon producer is losing money in a price war. An analyst at Guotai Haitong told us most of China’s listed market is still the old economy, with the new economy a small slice of it.
“The barriers to entry are gone. It’s going to come down to a price game.”
A fellow investor, after the Chengdu visits
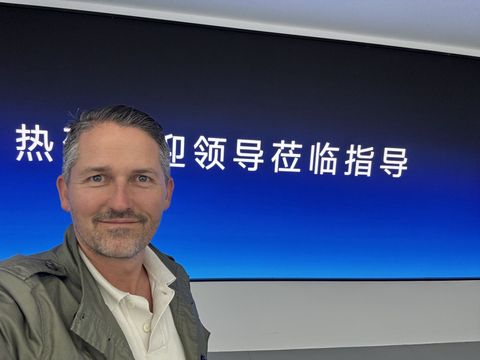
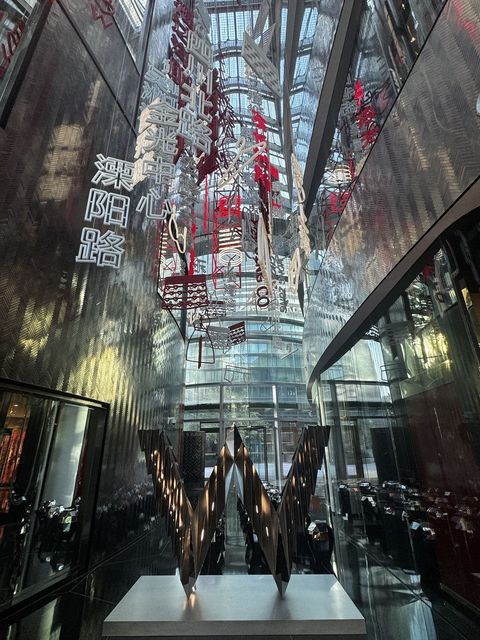
The state is part of every company we visited. One greeted us with the screen above, addressed to visiting officials. We treat that as a permanent feature of Chinese equities and price it in.
Five assumptions
- A grey, polluted country
- Quiet streets full of electric cars, buses and bikes, and clear autumn skies over the Great Wall.
- Unhappy people
- People who seemed content, busy and proud, in cities of more than 20 million that run smoothly. The system is still closed: you need a VPN to read most Western news.
- Suspicion of Westerners
- Warmth and curiosity at every stop.
- A copier, not an inventor
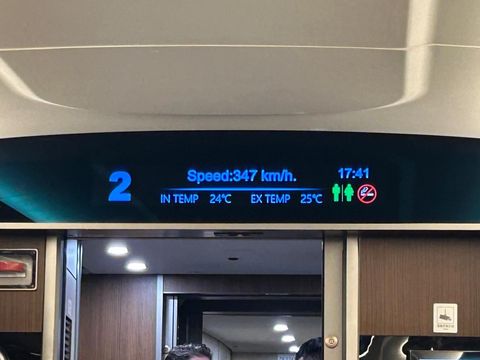
- AI models built on Chinese chips, automated car plants and a train at 347 km/h.
- An economy in trouble
- An uneven one. Manufacturing and technology are racing ahead; households are saving.
Payments and daily life
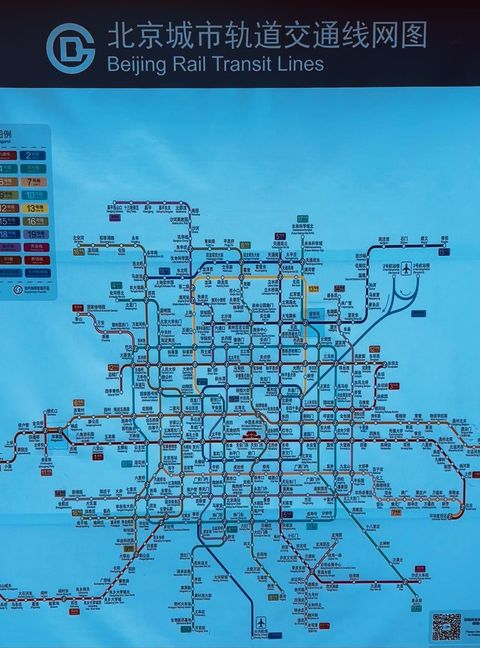
We did not use cash once in nine days. At a market stall we haggled with no shared language and paid on an Alipay terminal. Our Great Wall tickets were linked to our passports. 88.5% of China’s mobile-payment users pay by phone every day, and Meituan has delivered about 150 million orders in a single day.
We are applying the lesson at TRG: every form, signature and email in a client’s journey should earn its place.
By the numbers
- 30 600kmTravelled, about three-quarters of the way round the world.
- 347km/hTop speed on the Shanghai to Beijing train.
- 1.405bnPeople in China, about 22 times South Africa. The population fell by 3.4 million last year.
- 36 310Luckin Coffee stores, more than twice Starbucks’ US store count.
- 50 400kmHigh-speed rail, more than the rest of the world combined.
- 88.5%Of mobile-payment users pay by phone every day.
- 632mShanghai Tower, the tallest building in China.
- 5Days of annual leave a year, on average, at the 20 000-person brokerage we visited.
Food
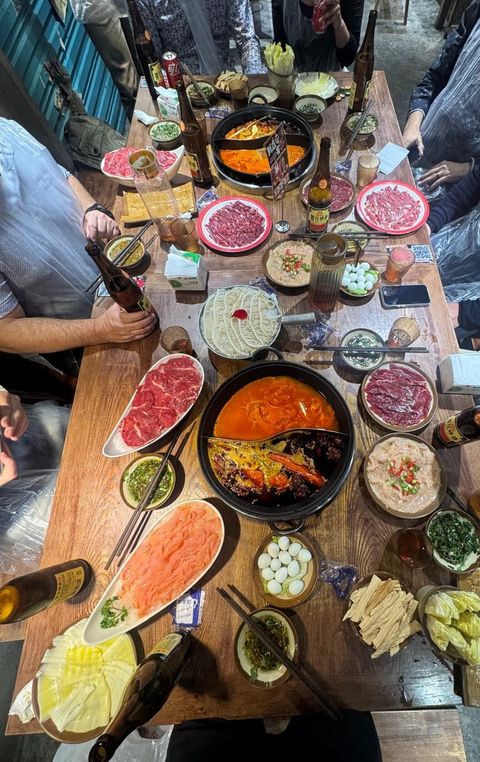
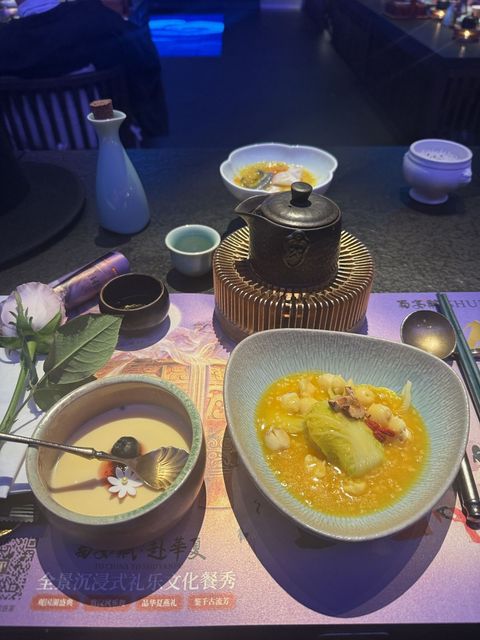
Our hosts made sure we ate like locals.
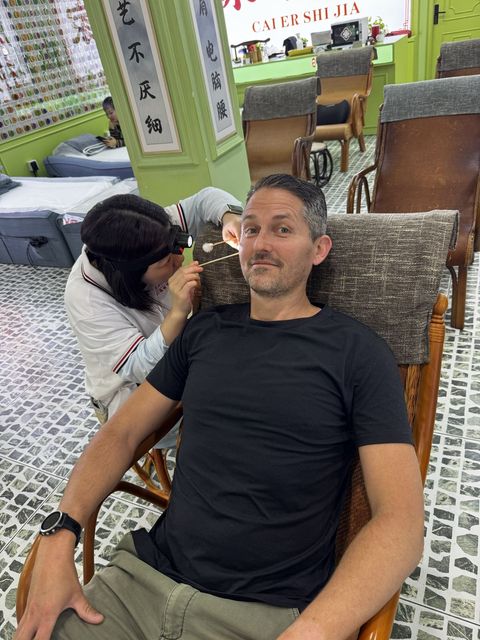
Chengdu’s ear-cleaning parlours work with picks, a goose feather and a tuning fork. We recommend them.
Your portfolio
China belongs in a diversified portfolio at a measured size. Onshore Chinese shares are owned mainly by local investors and follow their own policy cycle. Prescient’s data shows a correlation of 0.43 between the CSI 300 and the JSE, against 0.87 for emerging markets as a whole, and the CSI 300 trades on 14.7 times forward earnings against 21.1 for the S&P 500. The renminbi rose about 5% against the rand between February and September.
Because growth does not reliably turn into profit, we hold China through an active manager with a team in Shanghai rather than an index. Global Flex holds a small, deliberate allocation, and we are keeping it at that size. We would revisit it if foreign investment in Chinese shares were restricted, if controls on taking money out were tightened, or if tension over Taiwan escalated.
This was a nine-day tour of three of China’s wealthiest cities, with companies chosen by our host. Most of the country’s consumer stress sits in smaller cities we did not visit.
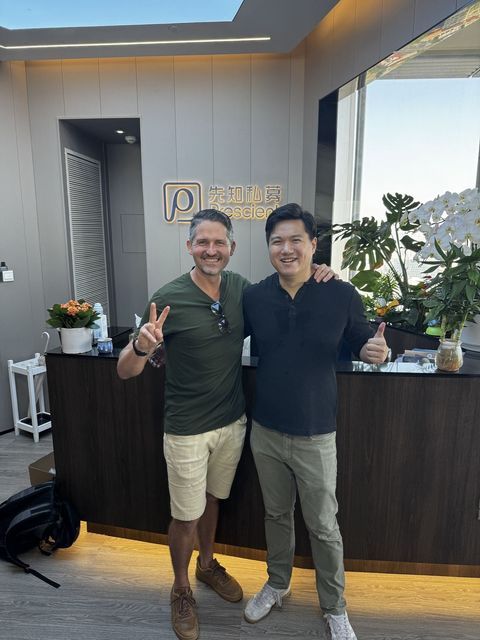
Devin ShutteHead of Investments and Director, The Robert Group
The tour was organised by Prescient Investment Management, which manages the Prescient China Balanced Fund held in TRG’s Global Flex portfolio and is the management company for TRG’s fund range. TRG paid all costs of the trip.
This article shares our views and observations for information only. It is not advice or a recommendation to buy or sell any investment and does not consider your objectives, financial situation or needs. Investments in foreign markets carry currency, liquidity, political and repatriation risks. Past investment performance is not necessarily indicative of future performance. Economic data from China’s National Bureau of Statistics and MSCI, to September 2026; market valuation, correlation and currency data from Prescient Investment Management; company figures from company filings and management presentations.
The Robert Group (Pty) Ltd is an Authorised Financial Services Provider and Crypto Asset Service Provider (FSP 41818). Reg No. 2010/003425/07.